


Life Insurance in Switzerland: Protect & Grow Your Assets
Life insurance in Switzerland is a key solution for financial planning and saving, helping protect your family against life’s uncertainties while building capital for the future.
Whether you want to secure your loved ones’ financial future, finance a property purchase, or prepare for retirement, working with a life insurance broker can help you find the coverage that best suits your needs from the wide range of options available on the market.
A Swiss life insurance policy offers unique flexibility by combining risk protection with an investment strategy. Discover how Invexa, your life insurance broker, can help you build a tailored, high-performing and tax-efficient solution.
Life Insurance at a Glance
- Dual Purpose: Life insurance can cover risks such as death and disability while also providing an opportunity to save and build capital.
- Tax Benefits: Souscrite dans le cadre du pilier 3a ou 3b, elle permet de réaliser d'importantes économies d'impôts selon votre canton de résidence.
- Family Protection: Beneficiaries in the event of death are clearly designated, ensuring the capital can be transferred quickly outside the standard estate process.
- Independent Advice: Working with a life insurance broker ensures an objective choice and helps negotiate the best terms and rates available on the Swiss market.
- Contract Costs: Differences in returns, fees, and coverage between products available on the Swiss market can amount to tens of thousands of francs over the life of a contract.
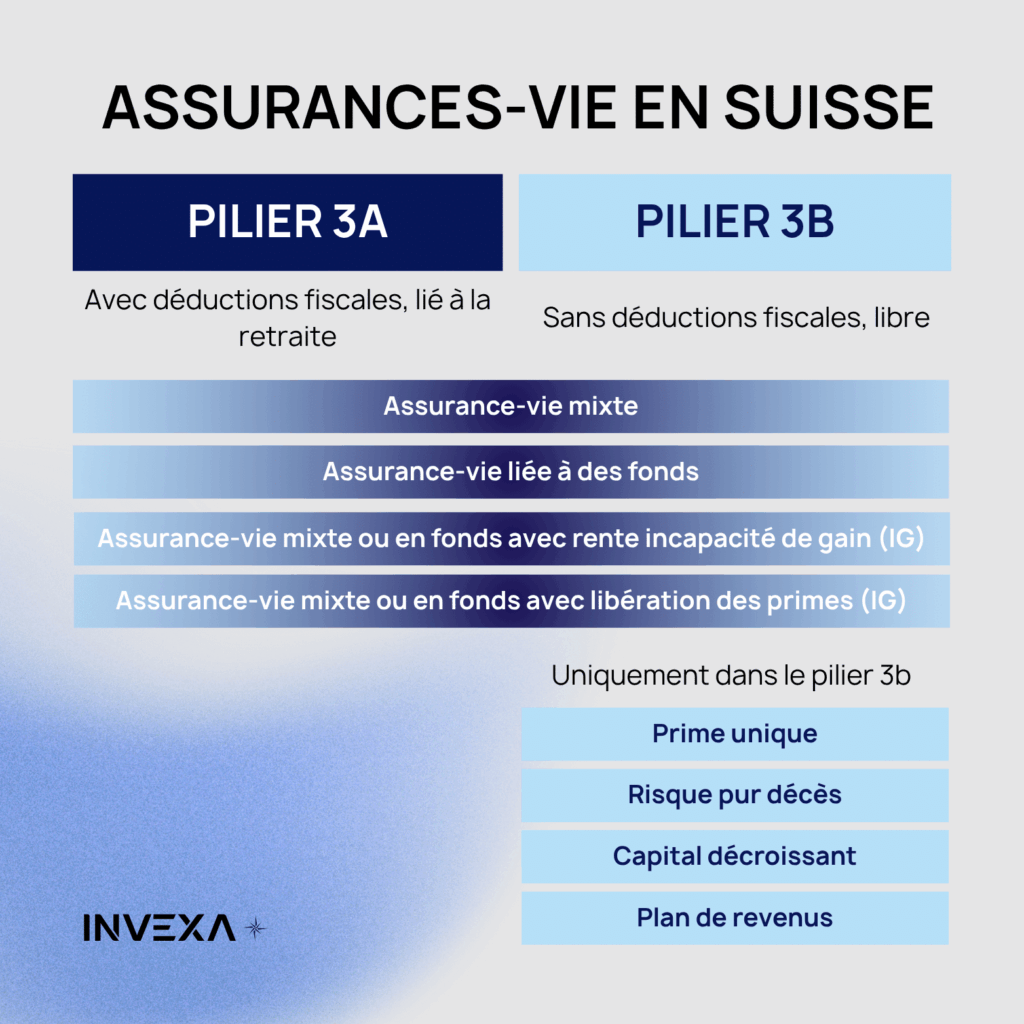
What Is Life Insurance in Switzerland?
A Swiss life insurance policy is a contract between a policyholder and an insurance company. In exchange for the payment of premiums (periodic or lump-sum), the insurer undertakes to pay a lump sum or annuity on an agreed date (in the event of survival) or when a specific event occurs (death or disability).
It plays a central role in the individual pension system (3rd Pillar) and comes in several forms to adapt to every stage of your life, from entering the workforce to estate planning.
Why Choose an Independent Life Insurance Broker?
360° Comprehensive Advice
Before making any recommendation, we conduct an in-depth assessment of your family, tax and financial situation. This forms the basis for advice that is genuinely tailored to your needs.
Independence and Objectivity
We have access to offers from all insurers operating in French-speaking Switzerland: AXA, Generali, Swiss Life, Groupe Mutuel, Helvetia and others, with no commitment to any of them.
Integrated Tax Optimisation
The choice between pure risk coverage, a mixed policy, Pillar 3a or unrestricted 3b pension provision has direct implications for your taxable income and taxation upon withdrawal.
Long-Term Support
Your professional, family and financial situation evolves. Your policies should evolve with it. We remain your single point of contact at every stage.
Types of Life Insurance in Switzerland
Il est crucial de distinguer les deux grandes familles d’assurances vie. Votre courtier vous orientera vers l’une ou l’autre (ou une combinaison des deux) selon vos objectifs.
1. “Pure Risk” Life Insurance
- Death Insurance: Pays a defined lump sum to the beneficiaries if the insured person dies. Ideal for protecting your family or securing a mortgage.
- Disability Insurance: Pays an annuity if the insured person becomes unable to work due to illness or accident, helping cover gaps in the 1st and 2nd Pillars.
- Key Feature: This type of policy has no surrender value (no savings component).
2. Capital-Building Life Insurance (Mixed Insurance)
It combines financial protection with a savings component. The death protection is significantly more affordable with this type of policy.
- Traditional Life Insurance: The capital is guaranteed at maturity with a fixed technical interest rate. It is the ultimate security solution.
- Investment-Linked Life Insurance: The savings component is invested in the financial markets. The risk is higher, but the long-term return potential is significantly greater.
Comparison: Pure Risk vs. Mixed Life Insurance
| Criterion | Pure risk life insurance | Mixed / investment-linked life insurance |
|---|---|---|
| Main purpose | Financial protection (death, disability) | Retirement savings + risk coverage |
| Surrender value | None (premiums are lost if the insured event does not occur) | Yes (the accumulated capital belongs to you) |
| Premium cost | Low to moderate | Higher (includes the savings premium) |
| Ideal for | Young families, homeowners, self-employed individuals | People looking to prepare for retirement while protecting their loved ones |
Life Insurance and Taxation: Pillar 3a or Pillar 3b?
Life Insurance Under Pillar 3a
The premiums paid are deductible from your taxable income up to the legal maximum (CHF 7,258 in 2026 for an employee).
Withdrawals are taxed at a reduced rate. However, withdrawal conditions are strict (retirement, home purchase, permanent departure from Switzerland).
Life Insurance Under Pillar 3b
It offers complete flexibility when it comes to withdrawals and beneficiaries. While premiums are generally not deductible at federal level, certain cantons such as Geneva and Fribourg offer significant tax deductions for 3b life insurance.
In addition, the payment of the capital at maturity is often tax-free under certain conditions.
Life Insurance Comparison: Pillar 3a vs. Pillar 3b
| Feature | Pillar 3a (Tied) | Pillar 3b (Unrestricted) |
|---|---|---|
| Main objective | Retirement savings and strong tax optimisation | Flexibility, medium-term goals and wealth transfer |
| Tax deduction | Yes. Deductible from income at federal and cantonal level (up to the legal maximum) | No at federal level. However, yes in Geneva (e.g. up to CHF 2,345 for a single person) |
| Capital availability | Restricted. Early withdrawal is limited (primary home purchase, departure from Switzerland, self-employment) | Free. Withdrawals are possible at any time (subject to the policy's surrender conditions) |
| Beneficiary clause | Strict. Defined by law (spouse, then children, etc.). Cannot be freely modified | 100% flexible. You choose who receives the capital (partner, friend, foundation), subject to statutory inheritance rights |
| Taxation at maturity | Taxed at a reduced rate, separately from other income | Tax-exempt if the pension conditions are met (contract held for more than 5 years, payout after age 60) |
How Does Inheritance Work with Life Insurance?
The beneficiary clause of a life insurance policy allows you to specify exactly who will receive the capital in the event of death.
However, the tax framework must be taken into account:
- Under Pillar 3a: The order of beneficiaries is strictly defined by law (spouse/registered partner first, followed by children, etc.). You cannot freely deviate from this order.
- Under Pillar 3b: You are completely free to designate the beneficiaries of your choice (partner, friend, association, etc.).
Beware of statutory inheritance rights: The surrender value of a mixed 3b life insurance policy may be subject to a clawback action if it infringes on the reserved shares of your legal heirs (children, spouse). By contrast, the capital from a pure risk death insurance policy generally falls outside the estate and is not subject to these reductions.
Your life insurance broker can review your estate planning situation.
Get Expert Advice
Taking out life insurance in Switzerland is a long-term commitment that should not be taken lightly. Choosing the insurance company, investment strategy (traditional or investment funds), and risk coverage requires careful analysis.
As a life insurance broker, we help you avoid common pitfalls, such as unnecessary overlapping coverage or choosing investment funds that do not match your risk profile.
Regulatory Framework and Quality of Advice
At Invexa, our advice operates within a regulated and recognized framework in Switzerland.
- Insurance intermediaries registered with FINMA
- Financial intermediaries under the FIDLEG, registered with ARIF
- Compliance with Swiss regulatory requirements
This ensures high standards of advice, transparency, and compliance.
Frequently Asked Questions About Life Insurance in Switzerland
Under which framework can I take out life insurance?
Life insurance can be taken out under Pillar 3a or Pillar 3b.
Why take out life insurance?
- Family and Loved Ones Protection: To provide beneficiaries with a lump sum or annuity in the event of death, helping them maintain their standard of living, pay off debts, or fund education.
- Retirement Planning: A whole life or investment-linked life insurance policy can be used to save for retirement while also providing death protection.
- Disability Coverage: Certain life insurance policies can protect against loss of income due to a disability caused by an illness or accident.
- Tax Optimization: Certain life insurance policies, such as those linked to Pillar 3a (individual retirement savings), offer tax advantages in Switzerland.
What is life insurance?
A life insurance policy is an insurance contract that allows you to save money and/or receive financial protection for yourself and your loved ones in the event of death or disability. It is often used for retirement planning, estate planning, and tax optimization.
What are the tax benefits of life insurance?
In Switzerland, life insurance can offer tax benefits, particularly when taken out under Pillar 3a (individual retirement savings).
The premiums paid are deductible from taxable income up to CHF 7,258 per year for employees and up to 20% of net income (capped at CHF 36,288 per year) for self-employed individuals. In addition, the accumulated capital is not subject to wealth tax as long as it remains in the 3a account. The capital is only taxed upon withdrawal, at a reduced rate.
In Geneva and Fribourg, contributions to a 3b insurance policy are deductible from taxable income. The amounts from 2026 are as follows:
- In Geneva: amounting to 2,345 CHF per year for a single person, 3'518 for a married couple (+959 CHF per child)
- In Fribourg: 750 CHF per year for an individual and 1,500 CHF for a married couple
How long does a life insurance policy last?
The term of a life insurance policy is defined from the outset and should be determined based on your risk coverage needs and investment horizon. It can generally range from 5 to 40 years.
If the policy is terminated before the end of the contract term, the cash surrender value may be lower than the premiums paid. It is therefore crucial to determine the appropriate term from the start. Here are the recommended policy terms:
- Term life insurance (death benefit only): Fixed term (5 to 30 years), ending upon death or at the end of the policy term.
- Mixed life insurance (savings + protection): Often between 10 and 30 years, sometimes extending until retirement.
- Tied Pillar 3a: Until retirement age(64–65), with early withdrawal possible under certain conditions.
- Investment-linked life insurance: Usually 10 to 30 years, but this depends on the investment.
- Whole life insurance: Provides coverage for the insured’s lifetime, with benefits paid upon death.
What is a surrender value?
The cash surrender value of a life insurance policy is the amount the policyholder can receive if they decide to cancel the policy before it expires. It primarily applies to life insurance policies with a savings component, such as mixed life insurance policies or investment-linked policies.
What are the different ways to pay life insurance premiums?
When purchasing a life insurance policy, the policyholder must choose how to pay the premiums. There are two main options: periodic premiums and a single premium.
An annual premium is a payment option in which the policyholder pays the premium annually, semiannually, quarterly, or monthly, depending on the payment schedule specified in the policy. A single premium is a one-time payment made at the start of the policy. This means the policyholder pays the full cost of the life insurance upfront.
Do you have to declare life insurance for tax purposes?
- Premiums paid,
- Cash surrender value (Pillar 3b only),
- Annuity payments received, and other factors.
Any gains may receive favorable tax treatment, but it is recommended that you consult your insurance broker to make sure you meet all applicable reporting requirements.
How can you withdraw money from a life insurance policy?
- When the policy reaches maturity: You receive the principal or annuity payments specified in the policy.
- Partial or full surrender: You may request to surrender the policy before its maturity date and receive its cash surrender value, potentially subject to fees or penalties.
- Special circumstances: Certain exceptional situations, such as disability or documented financial hardship, may allow for funds to be accessed under specific conditions.
How does profit sharing work?
Life insurers guarantee fixed benefits and premiums over long periods (20 to 30 years). To maintain this stability, they build in a safety margin by overestimating costs and underestimating investment returns. When actual results are better than expected, surpluses are generated:
- Risk premiums: Fewer claims than expected.
- Savings premiums: Higher-than-expected investment returns.
- Expense premiums: Actual expenses lower than expected.
Claire Fivaz
Get a Life Insurance Quote
Schedule a consultation with our experts, with no obligation, to explore life insurance options in Switzerland, assess your needs, and objectively compare the best options available.