


Pension Fund Buy-Ins at a Glance
- Objective: Voluntarily depositing capital into your pension fund to cover contribution gaps (years of study, late arrival in Switzerland, salary increase).
- Tax advantage The amounts paid are 100 % deductible from your taxable income in the year of payment.
- Yield: You increase your future benefits (retirement, disability, death) and this capital produces tax-free interest.
- 3-year rule: If you make a surrender, you cannot withdraw this capital in cash (e.g., for the purchase of a home) during the following 3 years.
- Ideal strategy: Spread your redemptions over several years to maximize the reduction of your tax progression.
What Is a 2nd Pillar Buy-In?
A buy-in to the 2nd pillar involves voluntarily paying an amount into your pension fund to fill pension gaps. These gaps can result from periods without pension fund coverage (such as studies, living abroad, or career breaks) or from switching to a pension plan with higher benefits.
Each pension institution determines the maximum amount you can buy in based on its regulations and your personal circumstances, including your age, insured salary, contribution period, and benefits already accrued.
Why Make a Buy-In to My 2nd Pillar?
1. Improved Benefits
The primary advantage of a buyback is the increase in pension capital. This capital will influence:
- The amount of the LPP pension that you will receive when you retire;
- Where is capital that you will be able to withdraw, if you choose a lump-sum payment or in the event of an EPL.
The earlier you make the buy-in during your working life, the more time your contributions have to benefit from interest and compounding within your pension fund. Over time, this can translate into a higher pension of several hundred francs more per month in retirement.
2. Tax Advantages
Amounts paid as part of a buy-in are fully deductible from taxable income at the federal, cantonal, and municipal levels (Art. 33 FTA).
3. Flexibility in Tax Planning
Unlike mandatory contributions, buybacks are optional and modular:
- You can them distribute over several years to optimize tax savings; ;
- You can choose the most opportune time (such as a bonus year, the sale of a property, or a drop in income, for example).
Tax Advantages of a Pension Fund Buy-In
The buy-in to the 2nd pillar offers exceptional tax benefits, making it one of the preferred tax optimization strategies for Swiss taxpayers with middle to high incomes.
Full, Unlimited Tax Deduction
Amounts paid as part of a buy-in are fully deductible from taxable income at the federal, cantonal, and municipal levels (Art. 33 FTA).
This deduction applies in the year the contribution is made and is reflected directly in your tax return.
Major advantage over the 3rd pillar: while pillar 3a caps the deduction at CHF 7,258 for employees (2026), buy-ins to the 2nd pillar have no annual limit. Your maximum buy-in amount depends solely on your pension gaps, which can amount to CHF 50,000, CHF 100,000, or even more depending on your circumstances.
This fundamental difference makes an occupational pension (BVG) buy-in the most effective tax-saving strategy for taxpayers who have already maximized their 3rd pillar contributions.
Calculating Your Actual Tax Savings
The tax savings generated by a buyout depend on three main factors:
- Your marginal tax rate: The higher your income, the higher the tax bracket you fall into. A lump-sum payment allows you to "drop down" into lower tax brackets, maximizing your savings.
- Your canton of residence: Tax rates vary considerably from canton to canton. Geneva and Vaud have higher tax rates than Valais or the canton of Zug, which increases the potential for tax savings.
- Your family situation: Married couples, single-parent families, and single people are subject to different tax brackets.
- In practice, the tax savings typically amount to 25% to 45% of the amount bought in.
A Concrete Example of Tax Savings
- Profile: Single, 42 years old, no children
- Canton: Vaud
- Taxable income: CHF 120,000
- Buy-in made: CHF 30,000
| Criterion | Without redemption | With buyback |
|---|---|---|
| Taxable income | CHF 120,000 | CHF 90,000 |
| Total taxes (federal + cantonal + communal) | ~CHF 32,000 | ~CHF 21,000 |
| Tax savings | – | CHF 11,000 (37 % from the buyback) |
Optimization Strategies
Spreading Buy-Ins Over Several Years
- Staying in more favorable tax brackets
- Maximize the total tax deduction
- Maximize the total tax deduction
Timing of buybacks
The timing chosen to make a withdrawal directly impacts its tax efficiency:
- Year of bonus or exceptional income: A buyout makes it possible to offset a one-time increase in income and avoid moving into a higher tax bracket
- Year of taxable real estate capital gain: Ideal for partially offsetting the tax liability on a real estate sale
- Before changing canton: If you are moving to a canton with lower taxes, make your buy-ins before leaving to maximize the deduction (and vice versa)
Coordinating With Pillar 3a
The optimal strategy generally consists of:
- First pour the maximum into the Pillar 3a (CHF 7,258 in 2026)
- Then perform buy-ins into the second pillar with the remaining funds available
This approach allows you to combine the benefits of both pillars while maximizing the overall tax deduction.
Since 2026 (for the 2025 tax year), it is also possible to make buy-ins to pillar 3a.
Watch Out for Tax Pitfalls
If you are considering an early withdrawal (buying property, leaving Switzerland, or becoming self-employed), avoid making any buy-ins during the preceding 3 years. The tax authorities may retroactively disallow the deduction, requiring you to repay the tax savings plus late-payment interest.
How Much Can I Buy In?
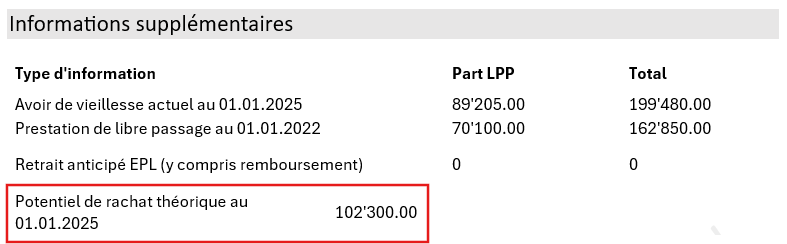
The maximum amount you can buy in is the difference between your theoretical retirement savings and your current pension fund balance. This difference represents your pension gap — in other words, the capital you would have accumulated had you always been affiliated with the same pension fund, with a constant salary and no interruptions.
The surrender value is shown on your pension certificate :
Drawbacks of a Buy-In
1. Locked Funds
If you're thinking about Withdraw your 2nd pillar balance, particularly for:
- For a departure early or regular retired,
- A real estate purchase through the Homeownership Incentive Program (EPL),
- Becoming self-employed
You must not have made a buy-in within the previous 3 years. Otherwise, the tax authorities can retroactively reclaim the taxes you saved through that buy-in, wiping out any tax benefit. This waiting period doesn't apply, however, if you receive your retirement benefits as an annuity. So if you're planning a withdrawal in the medium term, either postpone your buy-in or make it at least three years in advance.
2. Risk of Underfunding
A buy-in only makes sense if your pension fund is financially sound — that is, with a funding ratio above 100%. If the fund is underfunded (below 100%), it may apply recovery measures that also affect bought-in capital (reduced benefits, a lower conversion rate, etc.).
It's therefore advisable to ask your employer or the fund directly for its current funding ratio, and to avoid any buy-in if there's a persistent financial imbalance.
3. Limited Impact on Survivors' Pensions
In many pension plans, disability and survivors' pensions are calculated as a flat percentage of insured salary, rather than based on accumulated capital. In such cases, a buy-in will have no effect on these benefits.
If protecting your loved ones is your priority, a 3rd pillar or supplementary life insurance may be better suited.
Buy-Ins in the Event of Divorce
Under Swiss law, in the event of divorce, occupational pension assets (2nd pillar) accumulated during the marriage must be divided equitably (Art. 122 CC). This type of buy-in isn't subject to the 3-year waiting rule for withdrawals. In short, this means:
- The pension fund of one transfers a part of its occupational benefit assets to that of the other, to balance rights retired.
- The person who gives up a part of their property suffers a discount of his retirement savings.
The spouse whose occupational pension capital was reduced as a result of the transfer can, if they wish, buy back the transferred amounts to restore their previous level of pension provision.
Buying Back Contribution Years Using a Pillar 3a Withdrawal
You can transfer all or part of your 3a capital to your pension fund, provided that the remaining balance does not exceed the maximum buy-in amount. However, you will still have to pay the lump-sum withdrawal tax (one-fifth of the tax, taxed separately from your income at a reduced rate).
You can transfer all or part of your 3a capital to your pension fund, provided that the remaining balance does not exceed the maximum buy-in amount. However, you will still have to pay the lump-sum withdrawal tax (one-fifth of the tax, taxed separately from your income at a reduced rate).
Pension Fund Buy-In vs. Pillar 3a Contribution
A 2nd pillar buy-in lets you fill a contribution gap, with high amounts and a very advantageous tax deduction. However, any lump-sum withdrawal within the three years following a buy-in can result in the loss of that tax benefit.
The 3a pillar, on the other hand, offers greater flexibility. It allows you to build up retirement savings regularly, with an annual tax deduction limit. It is available to everyone, including self-employed individuals, and offers early withdrawal options similar to those of the 2nd pillar. It can take the form of a savings account or an investment fund, offering greater return potential than the 2nd pillar, but also greater risk. If you have already contributed the maximum amount to your pillar 3a, it may be worth considering buy-ins to your pension fund.
Can I Increase My Buy-In Potential?
EPL reimbursement: Prerequisite for tax-deductible buyback
If you've already used your 2nd pillar to help finance the purchase of your primary residence through home ownership promotion (EPL), this directly affects your ability to make new, tax-deductible buy-ins.
The Mandatory Prior Repayment Rule
As long as you haven't fully repaid an early EPL withdrawal, you cannot make tax-deductible buy-ins to your 2nd pillar. This rule exists to prevent people from using their pension assets for property ownership while simultaneously benefiting from tax advantages through buy-ins.
In concrete terms, if you withdrew CHF 80,000 from your 2nd pillar in 2015 to buy your home, you must repay that CHF 80,000 before you can make a buy-in that the tax authorities will recognize as deductible.
How EPL Repayment Works
Repayment of an early withdrawal for the purchase of a home can be made in two ways:
Voluntary repayment: You can voluntarily repay all or part of the withdrawn amount, at any time, up until 3 years before the ordinary retirement age (currently up to age 62 for men and 61 for women). The repayment can be:
- Full: you refund the entire withdrawal
- Partial: you repay part of it, though this doesn't yet entitle you to make deductible buy-ins
Frequently Asked Questions
Are withdrawals in the 2nd pillar tax-deductible?
Yes, buy-ins to the 2nd pillar are fully deductible from taxable income at the federal, cantonal, and municipal levels, in accordance with Article 33 of the Federal Direct Federal Tax Act (FTA). This deduction applies without an annual limit, unlike pillar 3a. The amount you buy in directly reduces your taxable income for the year in which the contribution is made.
For example, if you earn CHF 100,000 and make a contribution of CHF 25,000, your taxable income drops to CHF 75,000, resulting in an immediate tax savings of CHF 6,000 to CHF 11,000, depending on your canton and family situation.
What is the actual tax saving from a 2nd pillar buyback?
The tax savings generated by a buy-in generally amount to between 25% and 45% of the amount contributed, depending on three main factors: your marginal tax rate, your canton of residence, and your family situation. The higher your income, the greater your potential tax savings, as you are taxed at higher rates.
Does the tax deduction apply in the year of the redemption or the following year?
The tax deduction applies to the calendar year in which you make the contribution. If you contribute CHF 30,000 in November 2025, you can deduct this amount in your 2025 tax return, which you will file in spring 2026. To maximize your deduction, make sure the contribution is actually credited to your pension fund account before December 31.
Must an early EPL withdrawal be repaid before a new buyback can be deducted?
Yes, absolutely. If you have already made an early withdrawal under the home ownership scheme (EPL), you must fully repay the amount withdrawn before you can make new tax-deductible buy-ins. Until the repayment is complete, any buy-in you make will not be recognized as tax-deductible by the tax authorities.
Who can make a buy-in?
Anyone affiliated with a Swiss pension fund who has a pension contribution gap can make a buy-in. Restrictions apply to individuals who are joining a Swiss pension fund for the first time.
Can my employer require me to make a buy-in?
No, buy-ins to the 2nd pillar are always voluntary. Your employer cannot force you to make a buy-in under any circumstances. You are using your own personal funds to voluntarily contribute to your pension fund and fill your pension gaps.
Do not confuse voluntary buy-ins with restructuring contributions, which some underfunded pension funds may temporarily require. These restructuring contributions are mandatory and shared between the employer and employee, but they are also tax-deductible.
Is the surrender taxable at withdrawal?
Yes, like any pillar 2 asset, it is taxed at the time of withdrawal (as a lump sum or integrated into the annuity). However, the taxation remains advantageous because a reduced rate is applied in the event of a lump-sum withdrawal.
Should I make a buyback for early retirement?
It depends on whether you plan to withdraw the capital within the next 3 years. Otherwise, the tax deduction will be reversed, and the capital will be subject to substantial taxation.
In addition, early retirement is penalized by the pension fund through a lower conversion rate (for the pension).